social investing
for serious investors.
Portfolios you can audit. Live conversation on everything you can trade. Shares held in your name.
invest in what you think.
theses you can own.
A thesis is a claim about the world. Several portfolios hold it. No two express it the same way.
 AI capex keeps climbing
The largest cloud and AI companies keep raising their capital budgets for AI data centers, and each increase translates into orders further down the supply chain: accelerator chips, the high-bandwidth memory attached to them, the optical and Ethernet networking that links racks together, and the power and cooling hardware a dense AI cluster requires. Because this spending is committed in multi-year building programmes rather than quarter by quarter, the order flow to suppliers tends to be visible well before it shows up in their reported revenue. A portfolio under this thesis selects US-listed suppliers whose AI data-center products materially drive earnings — semiconductor designers, memory makers, networking and interconnect vendors, and the equipment and component firms that build the racks. It excludes the companies buying the capacity, and suppliers whose AI exposure is a small or incidental part of the business.
 AI runs short of memory and storage
AI training and inference are consuming memory and storage faster than manufacturers can add capacity. High-bandwidth memory for accelerators takes far more wafer area per bit than standard DRAM, so every HBM line that comes online crowds out server and PC DRAM supply. At the same time, inference caches and AI data lakes are pulling enterprise SSDs and nearline hard drives out of a market that was not built for this volume. The result is tightening supply, with prices and margins rising across DRAM, NAND and HDD at once. A portfolio under this thesis selects the companies that make memory and storage: DRAM and NAND producers, hard-drive manufacturers, and the suppliers they depend on to ship volume, including memory interface chip designers and memory test equipment makers. AI accelerator makers are buyers of this memory, not beneficiaries of its scarcity, and are left out.
 America builds a rare-earth industry
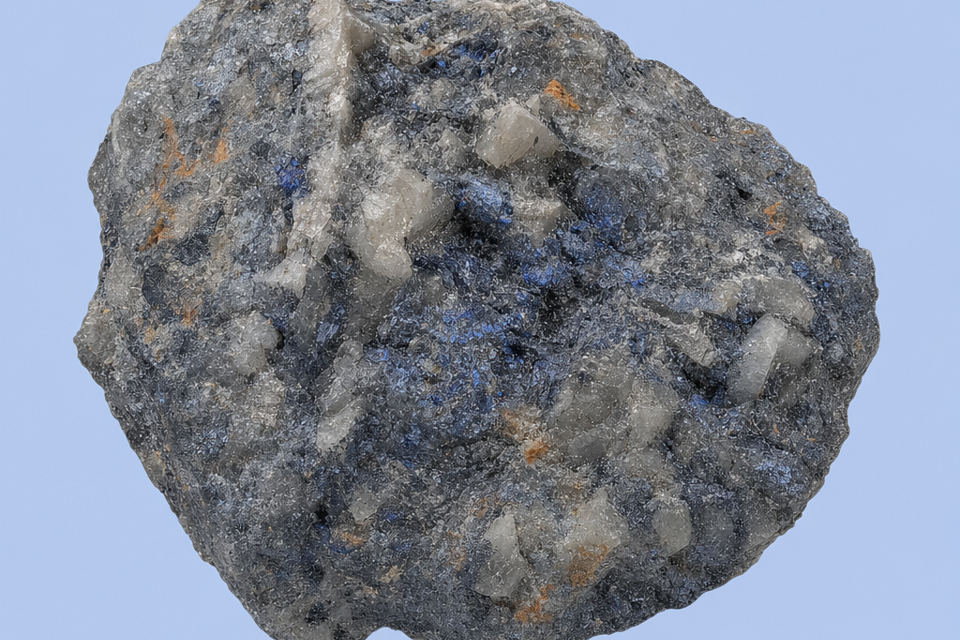
China separates most of the world's heavy rare earths and makes most of the sintered neodymium magnets that go into electric-vehicle motors, wind turbines, drones and guided munitions. The US government has started to treat that dependence as a supply problem it will pay to fix: Department of Defense grants, Department of Energy loans and offtake agreements are now underwriting domestic mining, heavy-rare-earth separation and magnet manufacturing. The question for this thesis is whether that financing turns announced projects into operating plants. A portfolio under it selects US-listed companies whose revenue is tied to that build-out: rare-earth miners and separators, magnet makers, and the processors and equipment suppliers they depend on. It favors companies with government contracts or financing already in hand, a credible path to production, and funding plans that do not rely on repeated share issuance to reach first output.
 Big Tech designs its own chips
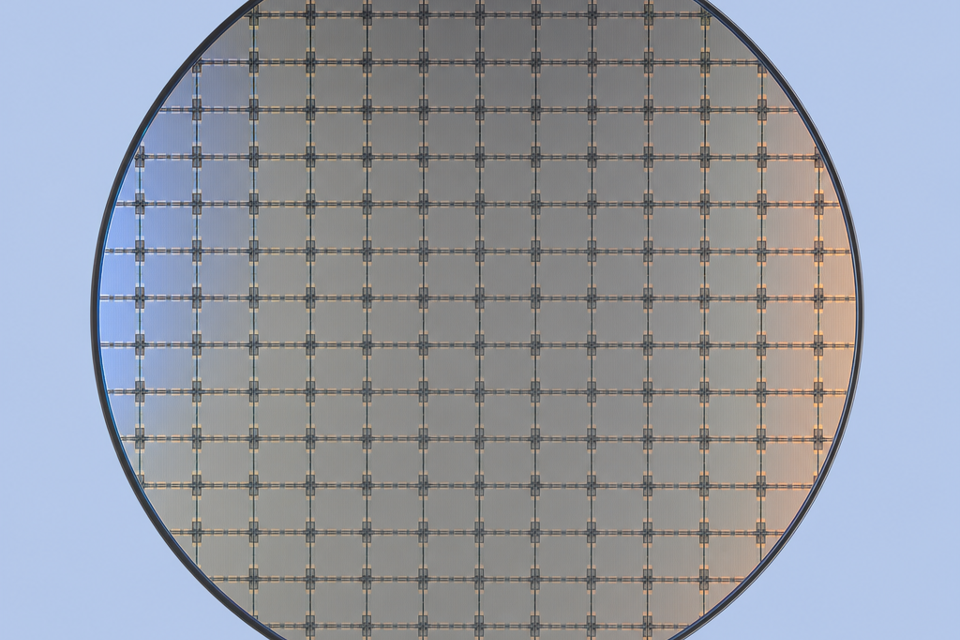
The largest cloud providers are designing their own AI accelerators rather than buying only general-purpose graphics processors. The motive is cost: a chip tuned to one company's workloads can run training and inference more cheaply per unit of compute than a merchant part bought at market prices. Each new generation of these in-house chips is paid for in advance, because the cloud companies do not build them alone. They hire custom-silicon design partners, license interface and processor IP, and book foundry and advanced-packaging capacity, and that spending now recurs with every annual refresh. A portfolio under this thesis selects the companies on the receiving end of those payments: application-specific chip designers that take a hyperscaler's architecture to production, licensors of memory, interconnect and core IP, and the foundries and packaging houses that manufacture the parts. Companies whose earnings depend materially on these programs qualify; makers of general-purpose AI graphics processors are excluded.
the tools, without the desk
Dig into the data, follow the construction, invest with the full picture. All free.
the room is open all day
A thread on everything you can trade, sitting next to the data.
own the portfolio
Every portfolio comes with its full record: what it holds, at what weight, and how it has performed. Read it, then put money behind it.